Study 02
A new launch is not a worse product. It is one sold at the expensive end.
Three lanes kept apart the whole way, because they are three different things a buyer can actually do. New launch means bought from the developer. Resale means owner to owner, never the developer. Every pair held strictly more than three years.
The headline
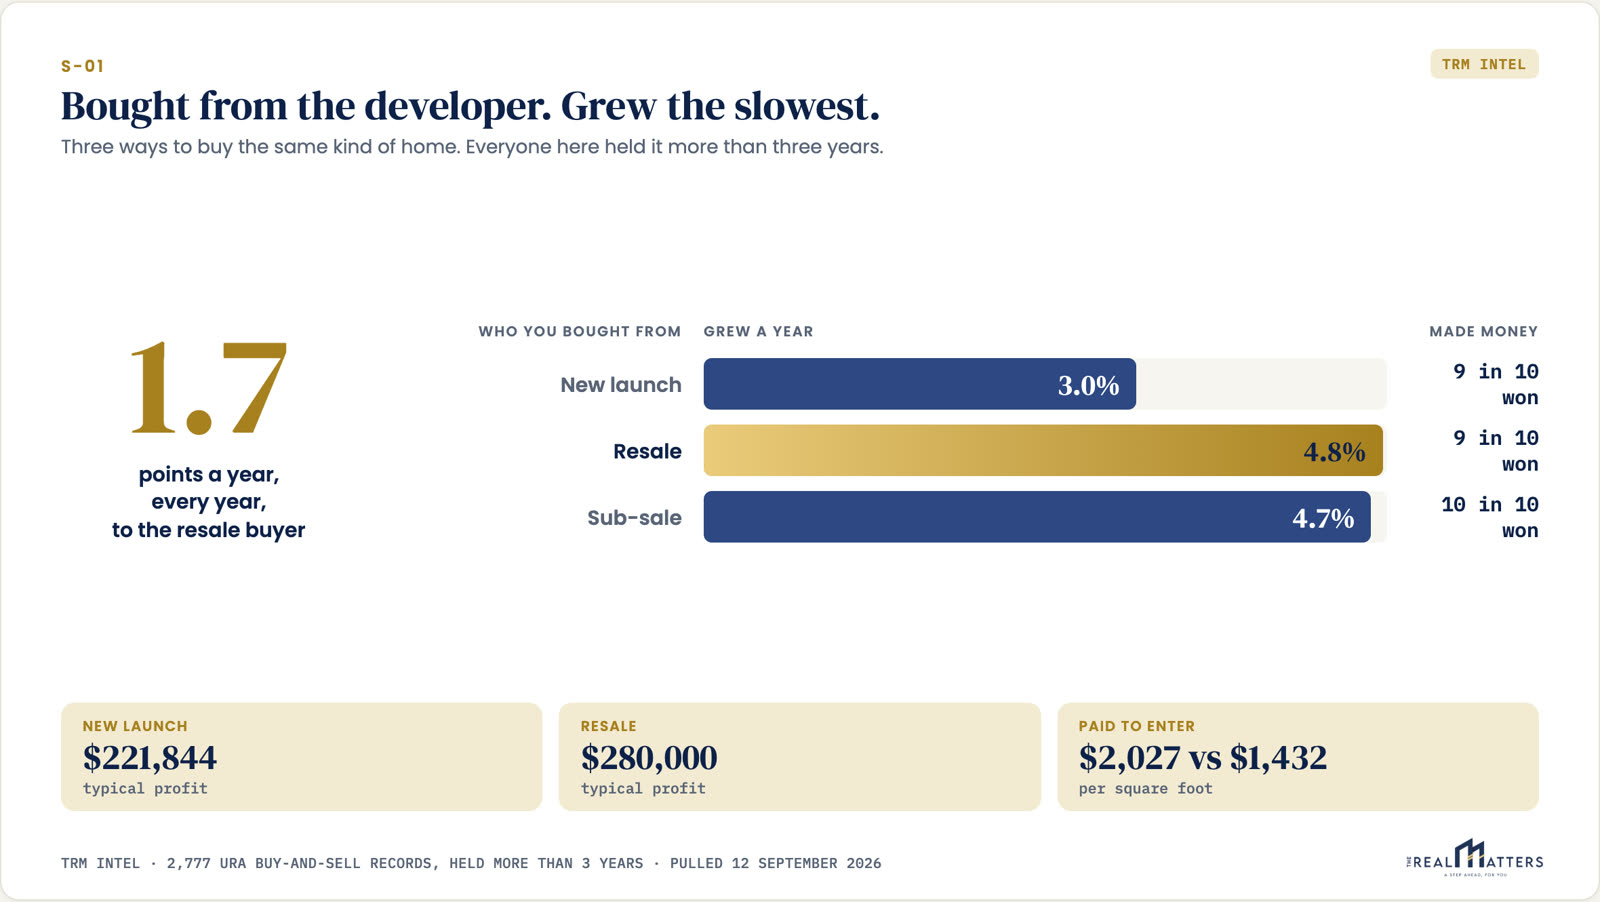
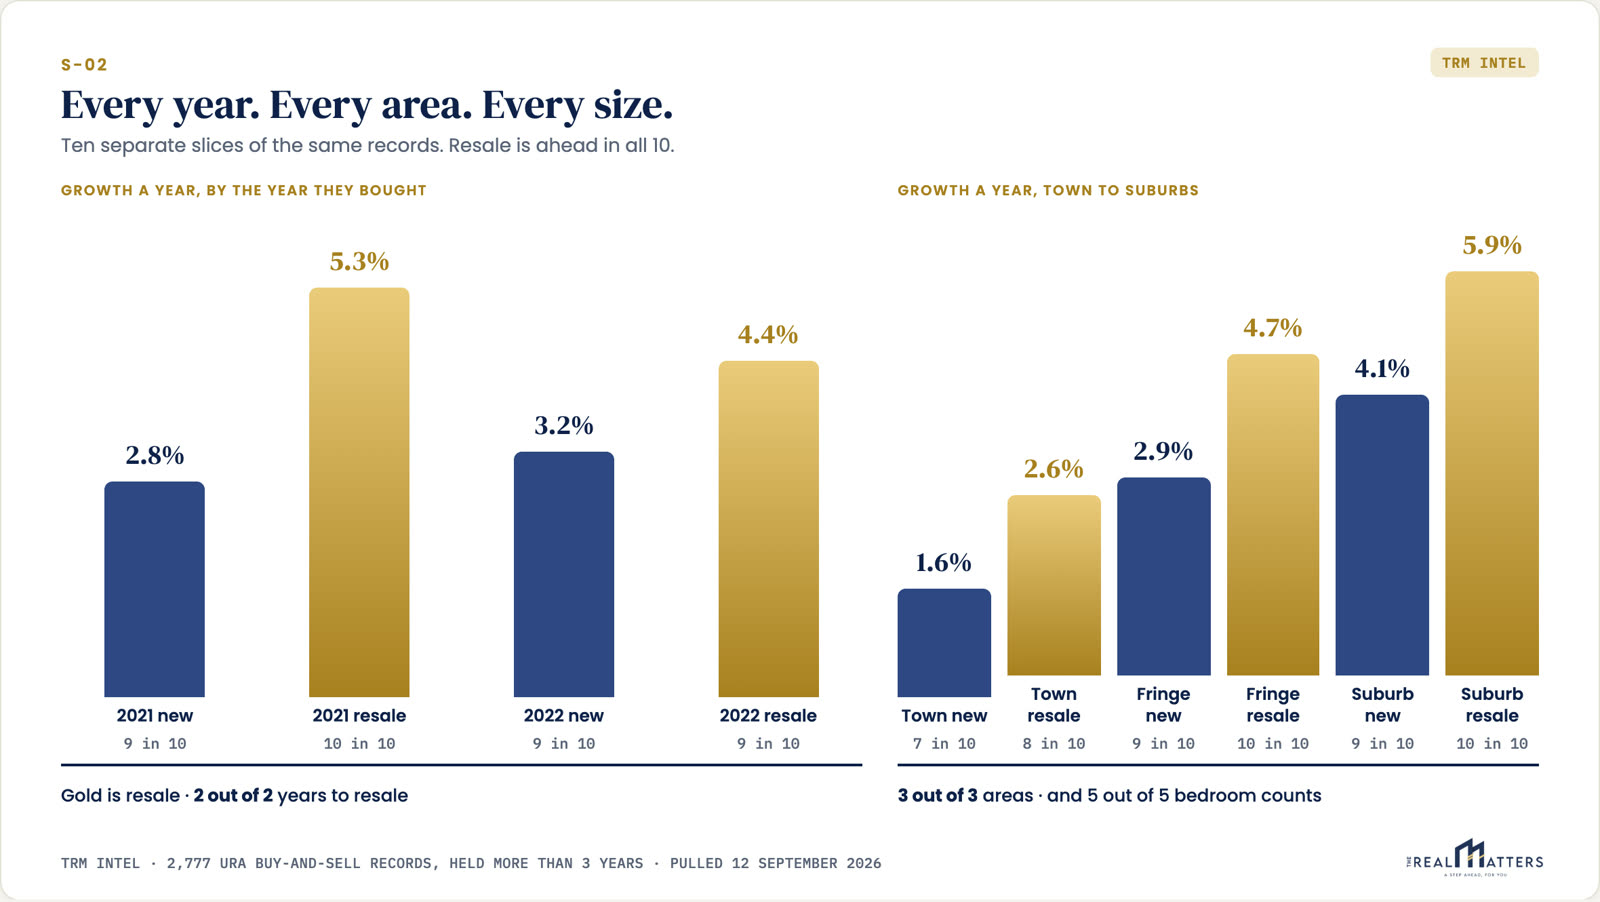
New launch grew 3.04 percent a year with an 89.2 percent win rate and a typical profit of 221,844 dollars, across 584 pairs. Resale grew 4.77 percent, 94.2 percent, 280,000 dollars, across 2,117. Sub-sale sat at 4.69 percent across 76. Resale led in ten of ten slices: two buying years, three segments and five bedroom counts. The loss tail is the sharper difference. 10.8 percent of new launch buyers lost money against 5.8 percent, and the unluckiest tenth was down 14,200 dollars against up 50,000.
The mechanism
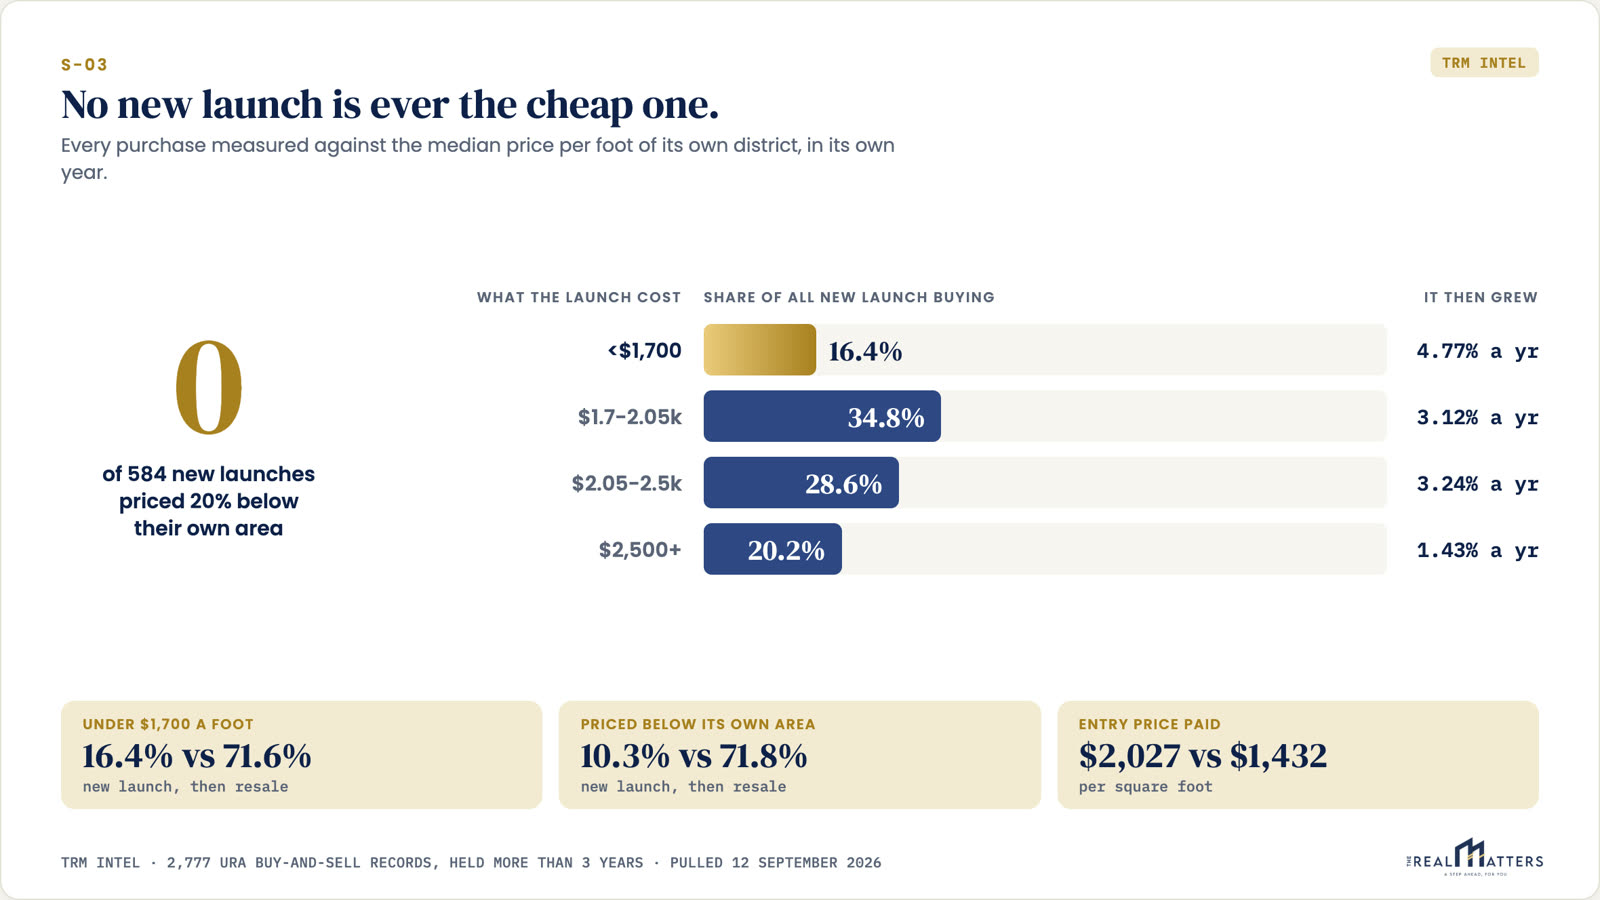
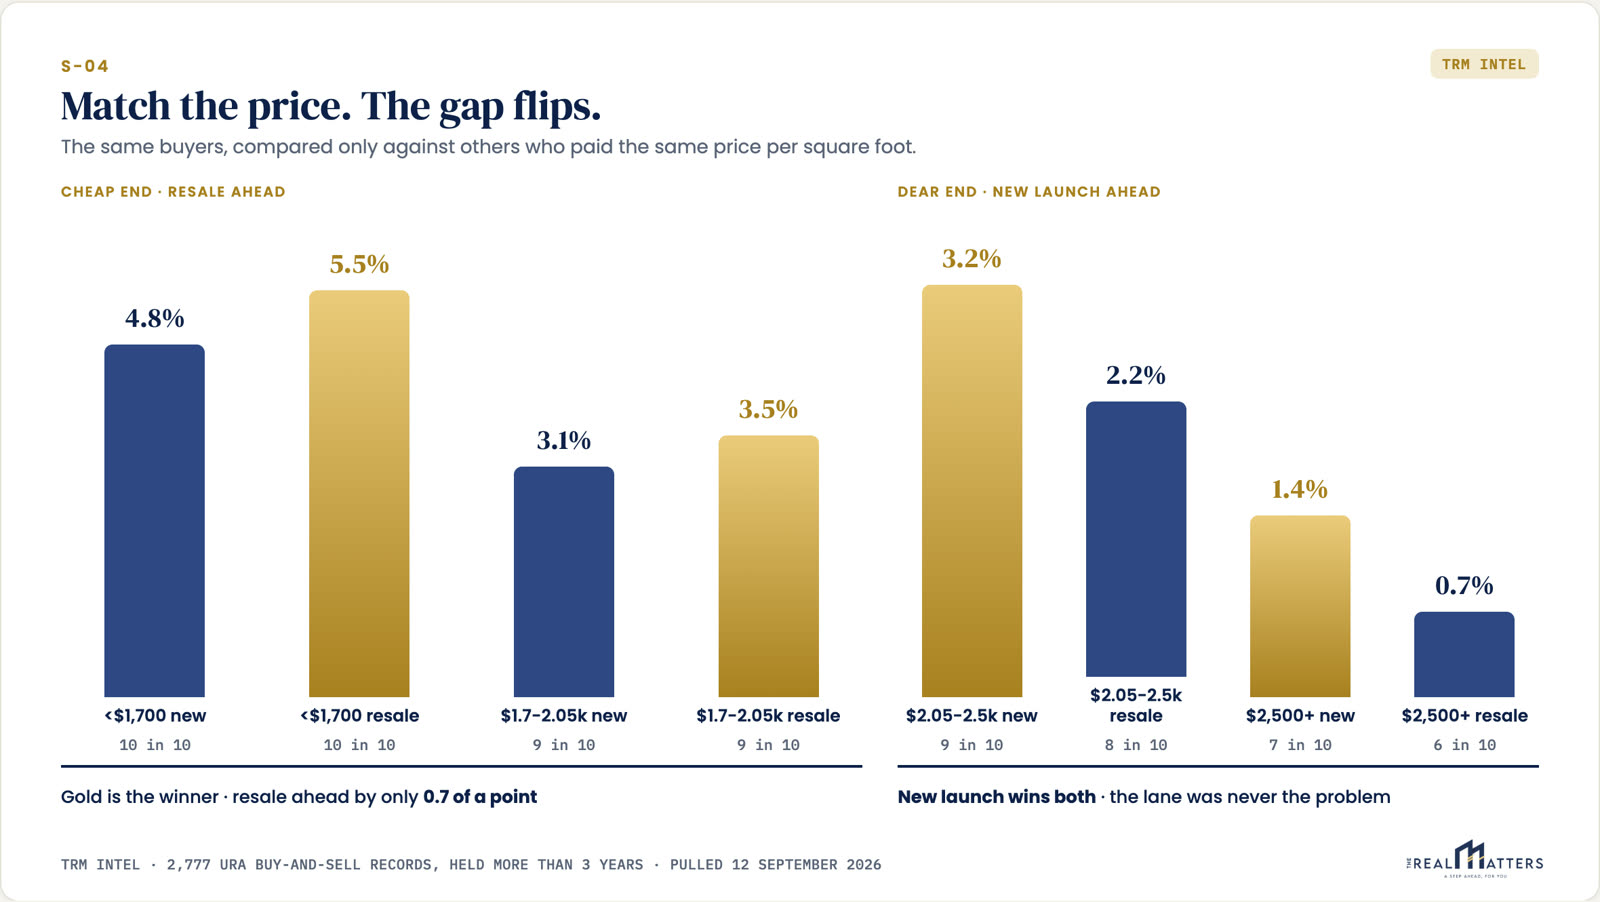
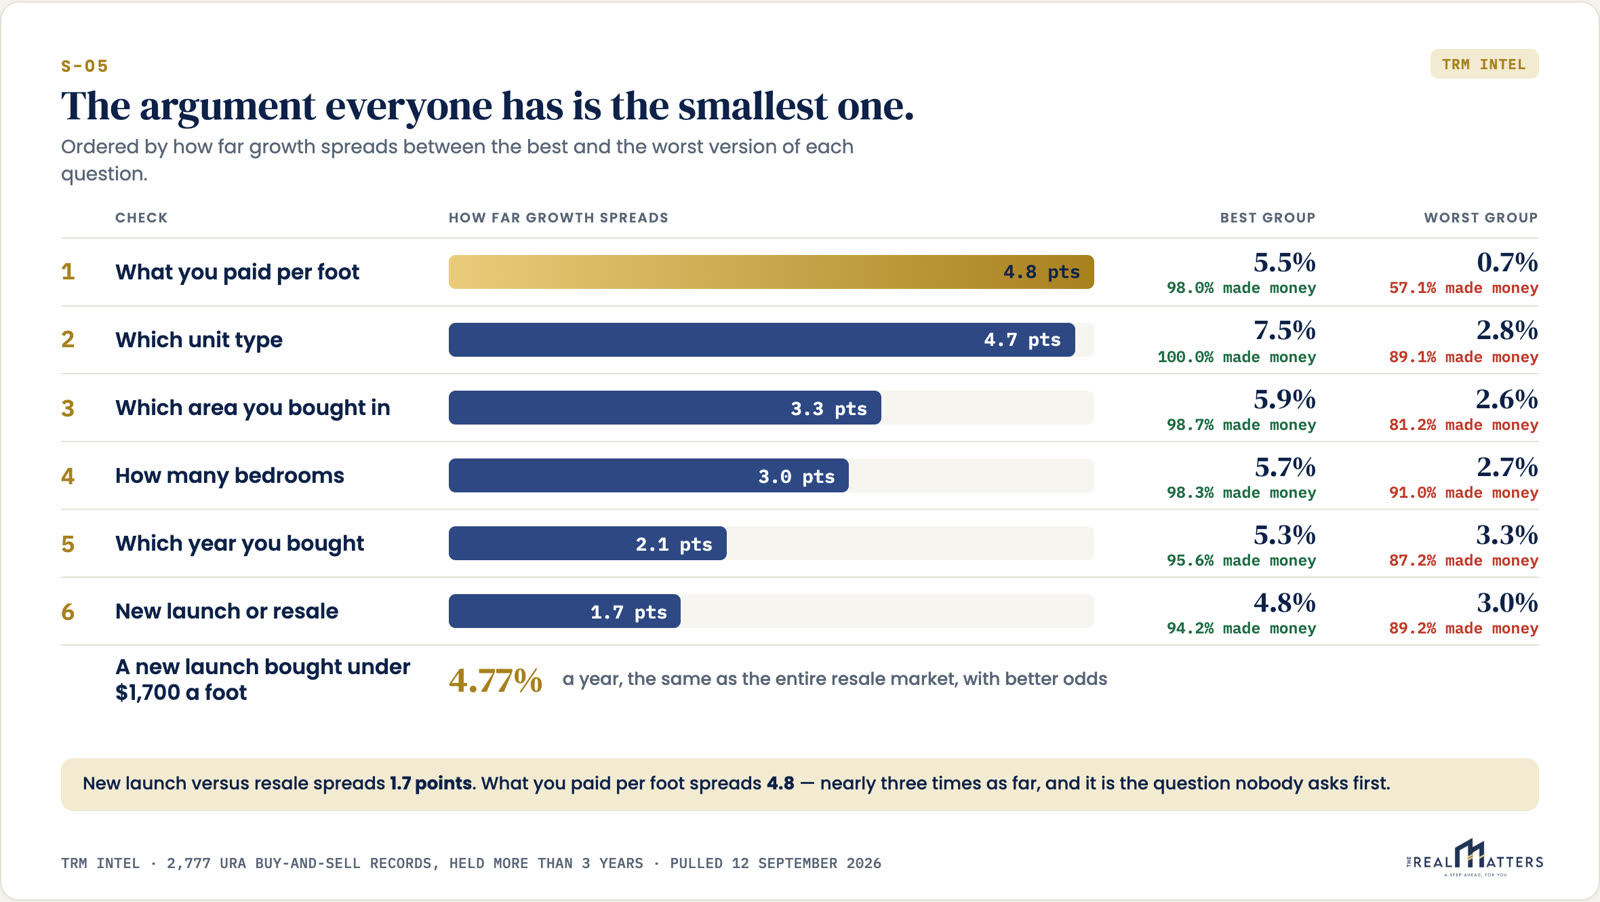
Only 10.3 percent of new launches were ever priced below their own district median, and not one of the 584 was more than 20 percent below. Resale managed that 658 times. 16.4 percent of new launch buying happened under 1,700 psf against 71.6 percent of resale. Put the two lanes at the same price and the story changes: under 1,700 psf resale leads by only 0.7 of a point, and between 2,050 and 2,500 psf the new launch wins, 3.24 against 2.17. Above 2,500 it wins again. So the question is never launch or resale. It is what you are paying relative to the street.
The "not never"
A new launch bought under 1,700 psf grew 4.77 percent, which is exactly the whole resale market rather than better than it, with better odds at 95.8 percent and a larger profit at 282,063 dollars. An earlier draft of this said "beat" and that was wrong, so it was corrected. Named launches track entry price the same way: Parc Clematis went in at 1,751 psf and returned 6.89 percent, Avenue South Residence at 2,280 psf returned 2.05.
The standout, and its boundary
Executive condo resale was the strongest result in the whole study, 7.45 percent a year across 189 pairs, every one of which made money, worst outcome still a 35,000 dollar gain, median entry 1,031 psf. Held at the same entry under 1,200 psf it still beat private resale. That result is about EC resale only. There are three new EC pairs at this cut, which is nothing, so this number must never be quoted as what a new EC launch returns.
The limits
What this study will not tell you.
01.
That new launches are a bad buy. The lane loses on average because of where it is priced, not because of what it is. Priced at the street, it performs like the street.
02.
Anything about new executive condominiums. Three pairs exist at this cut. The strong 189 pair EC figure is resale only and must not be read across.
03.
What your unit will do. Every pair here is somebody else who already bought and already sold, in one market cycle. It is a record, not a forecast.
Where these numbers come from
Computed from URA caveat records. 584 new sale, 2,117 resale and 76 sub-sale matched buy-and-sell pairs, held strictly longer than three years, caveats June 2021 to September 2026, pulled 12 September 2026. URA restates caveats for weeks after a month closes. Past transactions are not a forecast. Nothing here is financial advice.